 Untilfree
The FIRE Movement: What It Means and Where to Start
FIRE stands for financial independence, retire early. It is a way of thinking about money, built around one idea: save a big share of what you earn, invest it, and buy back your time.
What the FIRE movement is
The FIRE movement is a loose community of people who aim to own enough invested money that work becomes optional. There is no club, no official rulebook and no single leader. It grew out of personal finance blogs, forums and books, and it keeps changing as people share what worked and what did not. Most members agree on three habits: spend less than you earn, invest the difference steadily, and stay honest about the numbers.
"Retire early" is the catchy part, but plenty of people in the community keep working. They just no longer need the paycheck to pay for food, rent and bills. The goal is choice, not a beach.
Why spending is the centre of everything
Your FIRE number grows with what you spend, not with what you earn. Someone living on $2,000 a month needs a far smaller pot than someone living on $8,000, even if both earn the same. That is why the community talks so much about savings rate and everyday costs, and why the different "flavors" of FIRE are really just different spending levels.
Take someone spending $4,500 a month, or $54,000 a year. With the common 4% rule of thumb (explained in the FIRE number guide), that points to a pot of about $1.4 million. Cut spending by a quarter and the target drops by roughly a quarter, for good. Nothing about income changed.
Find your flavor
People use labels to describe the lifestyle they are aiming for. None of them has an official definition, and the dollar ranges vary by city and by person. The guide that matches your situation is below:
- Living frugally? Read the Lean FIRE number guide.
- Want comfort with room to spare? Try Chubby FIRE, the middle ground.
- Planning a generous lifestyle? See Fat FIRE.
- Want a smaller job instead of no job? Barista FIRE explains part-time plans.
- Already saved a lot early and want to stop adding? Coast FIRE is for you.
- Not sure which label fits? Compare all the types side by side in words.
- Just want the number? Start with your FIRE number.
- Choosing a tool? What to look for in a FIRE app lists the questions to ask.
- Thinking about leaving work sooner than 60? The retire early guides cover ages, bridge years and health cover.
Criticism worth hearing
FIRE is not perfect, and good advice includes the weak spots. Returns are not guaranteed. A long retirement faces more years of uncertainty than the research behind the 4% rule covered. Healthcare, taxes and family needs vary a lot between countries. And a plan that works on paper can feel different once the paycheck stops. The fix is not to give up, but to use cautious assumptions, check in regularly and keep a cushion.
How people actually get started
- Many people start by working out what they really spend, including the irregular costs.
- Next comes a rough idea of the lifestyle they are aiming for.
- Then a monthly amount to invest that they can sustain.
- Last, a look at the date it points to, revisited every few months.
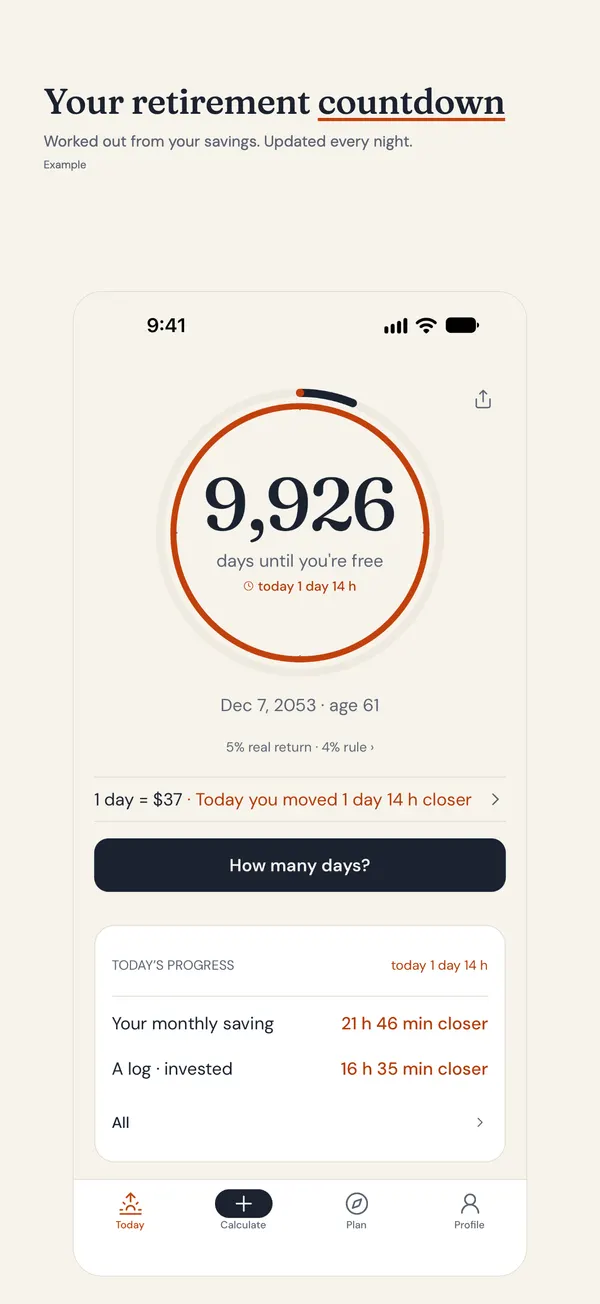
Untilfree does the last step for you: it turns those four numbers into a date and counts down the days.
Questions people ask
What is the FIRE movement in simple terms?
It is a community of people who save and invest a large share of their income so that, eventually, their investments can pay for their life and work becomes a choice. The retire-early part is optional.
What does FIRE movement mean for someone with an ordinary income?
It means your plan depends more on your spending and savings rate than on your salary. A modest income with low costs can reach independence, though it usually takes longer than a high income does.
How many types of FIRE are there?
There is no official count. The most common labels are Lean, Chubby, Fat, Barista and Coast FIRE. They mostly describe different spending levels or different ways of working along the way.
Is the FIRE community only for people in tech?
No. People from many jobs and countries take part. What they share is a habit of tracking spending and investing steadily, not a particular career or salary.
What is a FIRE calculator?
It is a tool that takes your savings, monthly investing and spending and estimates how long until your investments could cover your bills. Treat the answer as a range, because future returns are unknown.
Turn the idea into your own date
Four questions — your age, savings, monthly investing and monthly spending — and Untilfree gives you a date. Untilfree then counts down to the day your savings could pay your bills.
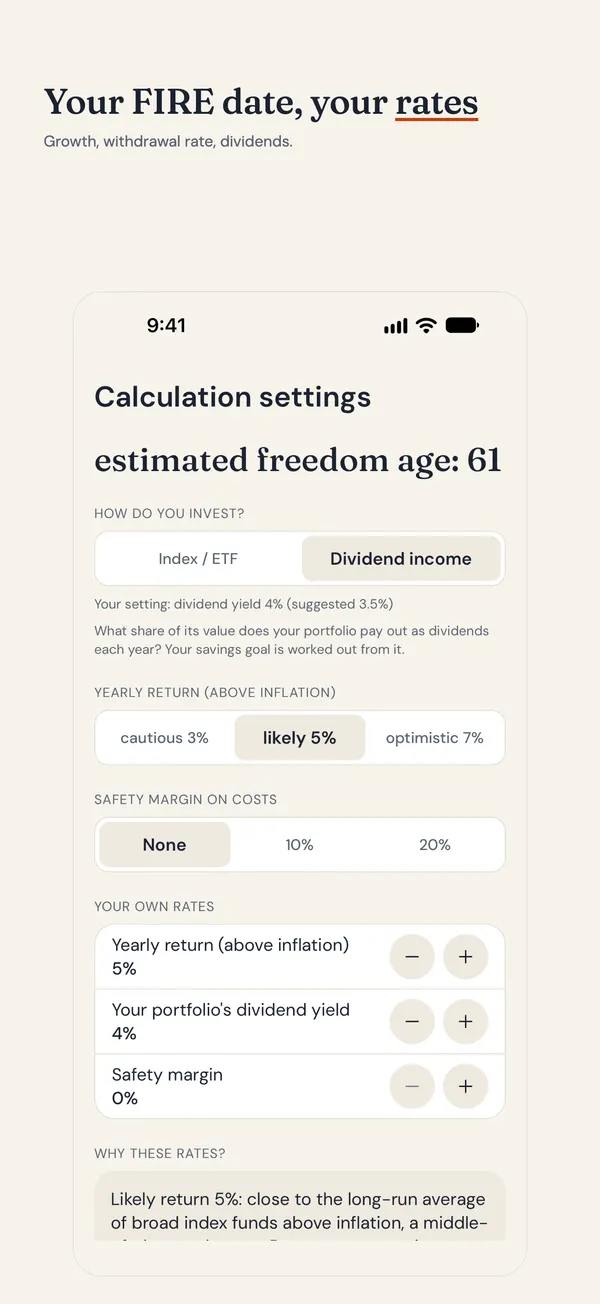
- Your freedom day, with a cautious, likely and optimistic range
- Pick index funds (4%) or dividend income (3.5%), and adjust the rate
- No account and no bank link; numbers stay on your phone
App Store · Free · Ads, optional Plus · No account · No bank link
Untilfree gives estimates in today’s money (after inflation). Taxes and state pensions are not included. This page is general information, not investment advice.
Published · by Srofia