 Untilfree
Retiring Early in Canada: TFSA, RRSP, CPP and OAS
FIRE works the same way in Canada, but the accounts are different. Most Canadian plans use two of them, a TFSA and an RRSP, and the order you draw them down matters as much as how much is in each.
Two accounts, two jobs
- TFSA (Tax-Free Savings Account). The 2026 limit is $7,000, and unused room carries forward from the year you turned 18. Growth and withdrawals are tax-free, you can take money out at any age, and what you take out is added back to your room the next year. This is what usually pays for the early years.
- RRSP (Registered Retirement Savings Plan). You can put in 18% of last year’s earned income, up to $33,810 for 2026. Contributions lower your taxable income now; withdrawals are taxed as income later. You can take money out at any age, but by the end of the year you turn 71 the RRSP has to become a RRIF (or an annuity), which pays out a minimum each year.
Unlike the UK or Australia, Canada does not lock retirement savings until a set age. The trade-off is tax: an RRSP withdrawal in a year with little other income is taxed lightly, which is why early retirees often draw from the RRSP in their low-income years and keep the TFSA for later or for big costs.
CPP: from 60 to 70
The Canada Pension Plan normally starts at 65. You can take it from 60, with the payment cut by 0.6% for each month before 65 (36% at 60), or wait until 70 for 0.7% more per month (42% more at 70). The maximum at 65 in 2026 is about $1,508 a month, but few people get it: the amount depends on how many years you paid in and how much you earned, so years of early retirement lower it. Your My Service Canada Account shows your own estimate.
OAS: 65, not earlier
Old Age Security starts at 65 for most people who have lived in Canada for at least 10 years after age 18, and cannot be taken earlier. You can delay it to 70 for up to 36% more. A full OAS needs 40 years of residence, and higher incomes have part of it clawed back.
How the pieces fit
A typical Canadian early-retirement plan has three stages:
- Stopping work to 60–65: live on taxable and TFSA savings, plus small RRSP withdrawals to use up the low tax brackets.
- From 60–65: CPP and then OAS start, and the savings need to cover less each year.
- From 71: RRIF minimums begin, so what is left in the RRSP has to come out on a schedule.
Many plans count the full spending in the FIRE number and treat CPP and OAS as a safety margin. Others lower the number once the pensions start; that is a choice about how much risk you want.
Priya is 38 and spends C$4,000 a month. At 4% her number is about C$1.2 million. If she stops at 50, her TFSA and a small RRSP draw have to carry her for at least 10 years before CPP, and 15 before OAS. Untilfree gives her one date for the total; how she splits it between accounts is a separate decision.
The 4% figure comes from US data; some Canadian planners prefer 3.5% for retirements longer than 30 years. See the 4% rule explained.
Questions people ask
How much do I need to retire early in Canada?
A common starting point is 25 times your yearly spending. Spending C$48,000 a year points to about C$1.2 million. CPP and OAS can lower what your savings must cover from 60–65.
Should I use a TFSA or an RRSP for early retirement?
Most plans use both. The RRSP gives a tax break now and suits years with low income later; the TFSA is tax-free to withdraw at any age, which makes it flexible for the early years.
Can I take CPP early?
Yes, from 60, with the payment reduced by 0.6% for each month before 65, so 36% less at 60. Waiting until 70 adds 0.7% a month.
When does OAS start?
At 65. It cannot start earlier, and you can delay it to 70 for up to 36% more.
Does Untilfree include CPP, OAS or tax?
No. Untilfree counts your savings only, before tax, in today’s money, and leaves out government pensions. You can set the currency to Canadian dollars; amounts are not converted.
One date for your whole plan
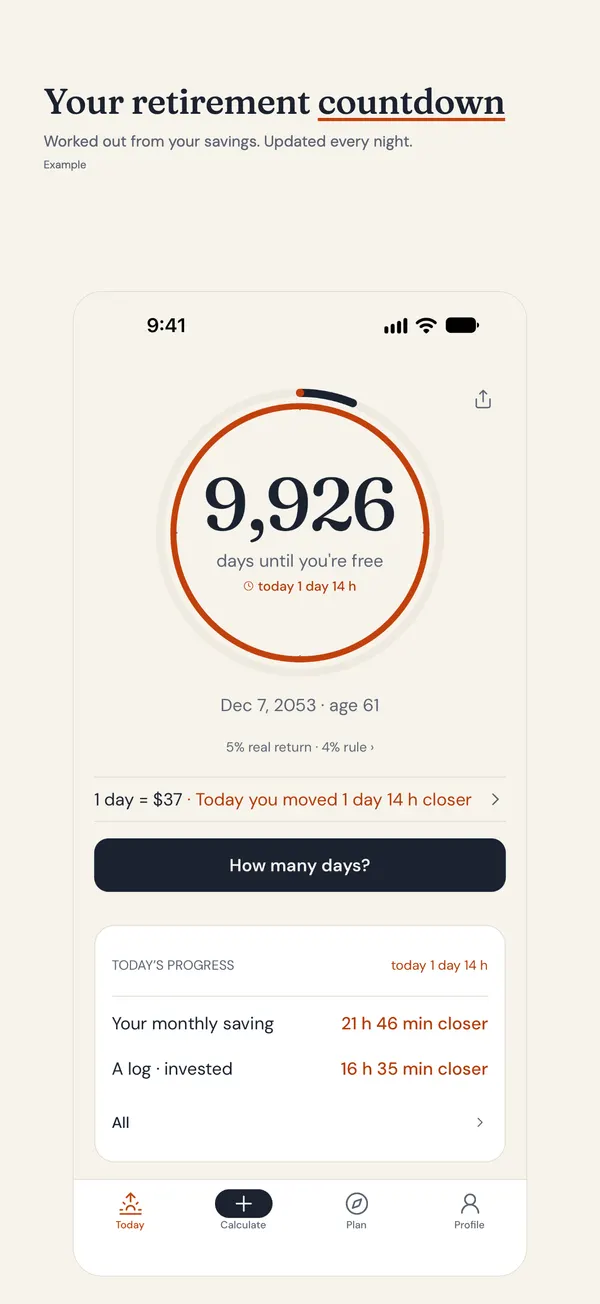
Enter your total savings, monthly investing and spending. Untilfree shows the date your savings could cover your bills and counts down to it.
- Amounts shown in your currency
- Withdrawal rate or dividend yield, free to change
- No account and no bank link
App Store · Google Play · Free · Ads, optional Plus · No account · No bank link
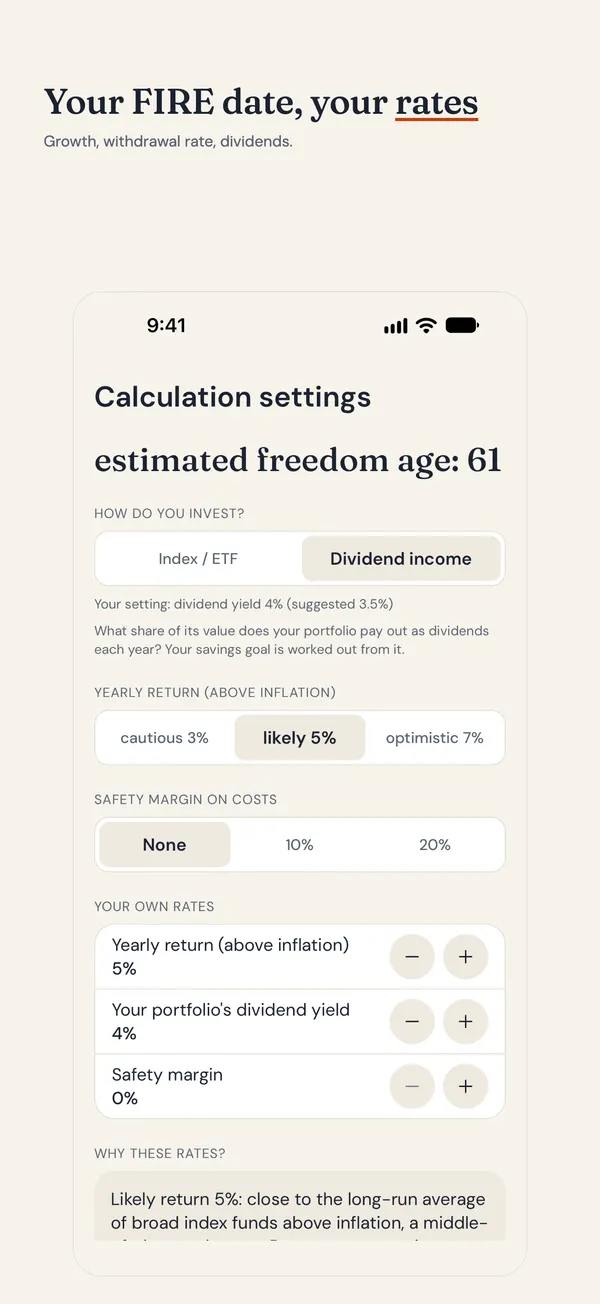
Untilfree gives estimates in today’s money (after inflation). Taxes, CPP and OAS are not included. Limits are for 2026. This page is general information, not investment or tax advice.
Published · by Srofia