 Untilfree
Debt Snowball vs Avalanche: Which Is Better?
Both methods pay every minimum and send the extra to one debt at a time. The only difference is which debt goes first, and that changes both the interest and how it feels.
The two methods
- Snowball: pay the smallest balance off first, then roll its payment into the next smallest. Quick wins keep you going.
- Avalanche: pay the highest interest rate off first. It costs the least interest in total.
In both, every other debt still gets its minimum payment, and nothing new is added to the cards.
A worked example
Three debts and $600 a month to pay them:
| Debt | Balance | Rate | Minimum |
|---|---|---|---|
| Card A | $5,200 | 26% | $130 |
| Store card | $900 | 18% | $30 |
| Personal loan | $6,000 | 12% | $200 |
- Snowball: the store card is gone in month 4, Card A in month 19, everything in month 25. Total interest about $2,340.
- Avalanche: Card A is gone in month 17, the store card in month 19, everything in month 24. Total interest about $2,240.
Avalanche wins by about $100 and one month here. Snowball gives a first win in month 4 instead of month 17. The bigger the rate gap between debts, the more avalanche saves.
Which one to pick
If you trust yourself to stick with it, avalanche is the cheaper plan. If you have tried before and stopped, the early win of snowball is worth a little interest. Either is far better than paying minimums with no plan. The calculator above shows how long the first debt takes on its own.
After the snowball
When the last debt is paid, the whole $600 is free. Invested every month instead, that is the start of the next countdown: the day your savings could cover your bills.
Jess tried paying off cards before and gave up. This time she picks snowball, clears the store card in four months, and keeps going. Two years later she is debt-free and moves the $600 straight into investing.
Questions people ask
Is the snowball or avalanche method better?
Avalanche costs less interest. Snowball gives quicker wins, which helps some people keep going. In our example the difference was about $100 and one month.
What is the debt snowball method?
Pay minimums on everything and put every extra dollar on the smallest balance. When it is gone, roll that payment into the next smallest.
What is the debt avalanche method?
Pay minimums on everything and put every extra dollar on the debt with the highest interest rate, then the next highest.
Which method pays off debt faster?
Usually avalanche, by a little, because less goes to interest. When the smallest debt also has the highest rate, both give the same plan.
What should I do after paying off debt?
Keep the payment going, but to yourself: invest it. That money now shortens the road to financial independence.
After the last payment, the countdown starts
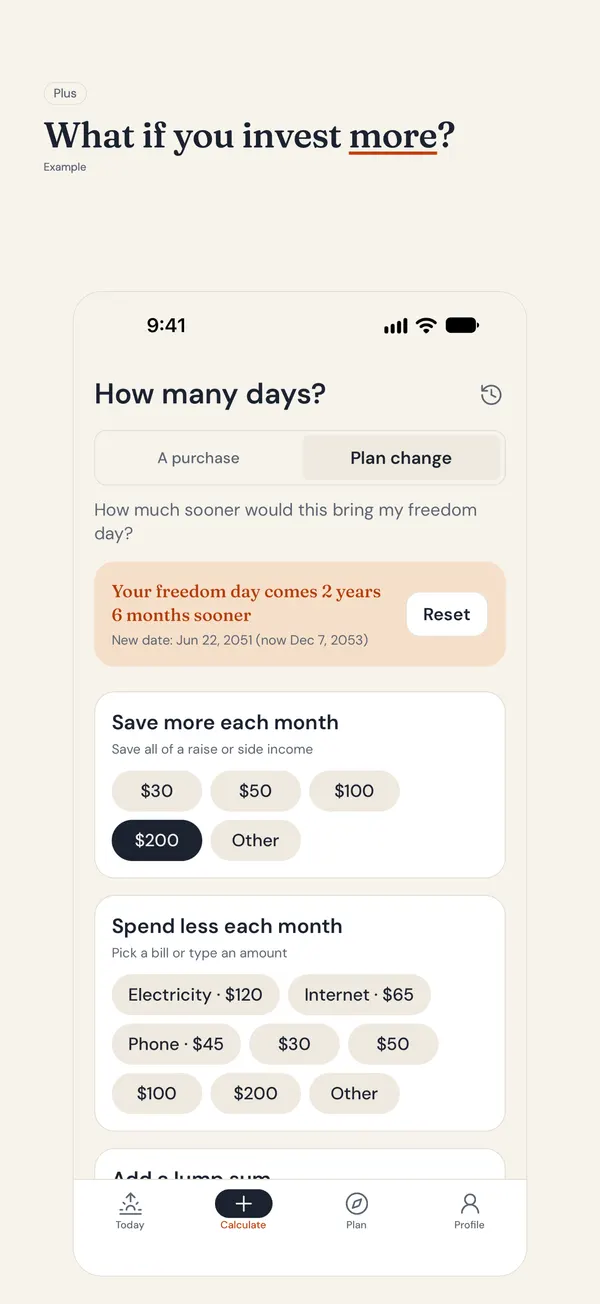
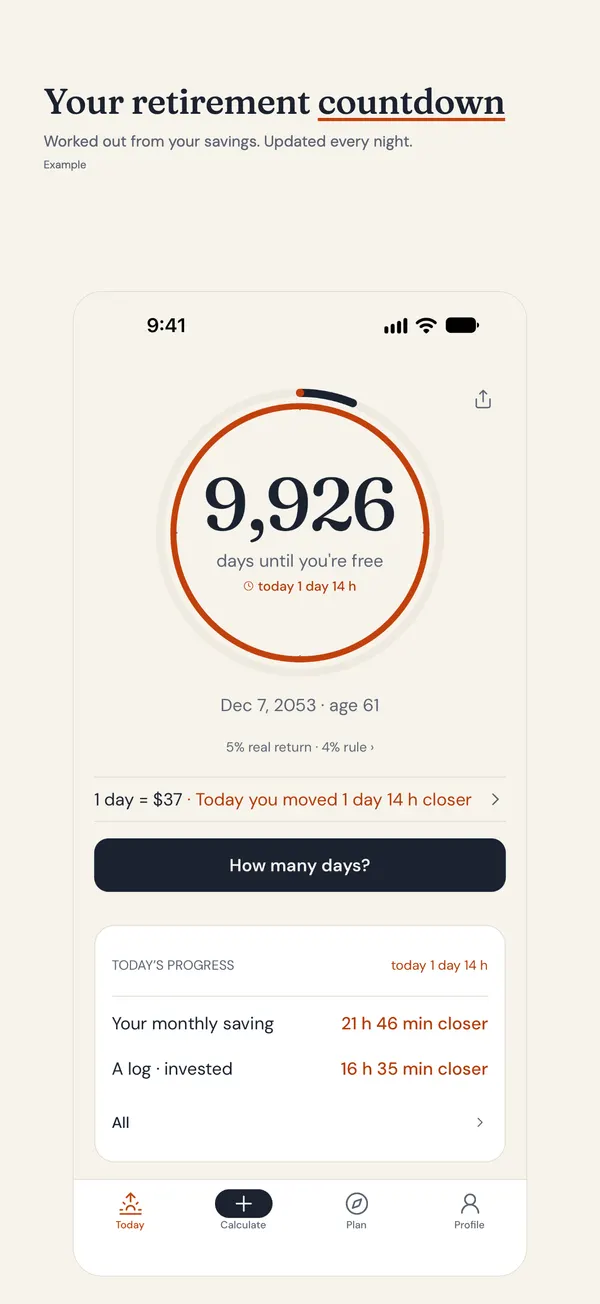
Untilfree does not track debts. It answers the next question: when could you stop working? Enter your savings minus what you owe, and what you can invest each month. When a debt is gone, use What if to add the old payment to your investing and see how much sooner your freedom day comes.
- Savings can start below zero
- What if shows the date with the old payment invested
- No account, no bank link
App Store · Free · Ads, optional Plus · No account · No bank link
Untilfree gives estimates in today’s money (after inflation). Taxes and state pensions are not included. This page is general information, not investment advice.
Published · by Srofia