 Untilfree
Is $500,000 Enough to Retire On, and for How Long?
The honest answer is "it depends on your yearly spending", and the gap between a lean year and a loose one is huge. Here is how $500,000 behaves at different spending levels.
How much income can $500,000 generate?
A common rule of thumb is to draw a fixed share of your pot each year. At 3%, $500,000 pays about $15,000 a year. At 3.5%, about $17,500. At 4%, about $20,000. That is roughly $1,250 to $1,650 a month, before tax, in today's money.
For most people in big cities that is not a full living. For someone with very low costs, a paid-off home, or other income, it can be a real base. This is why Lean FIRE people watch their costs so closely.
Lasts for good, or runs out?
There are two different ideas hiding in "how long will it last".
- Lasts for good. You draw so little that, by the usual 4% rule of thumb, the pot should keep going. At $500,000 that means about $20,000 a year or less.
- Lasts for a number of years. You spend more, so the pot is slowly used up. How many years depends on how much you take and how your investments grow.
Three spending levels
Assuming the pot grows 5% a year after inflation (an assumption, not a promise), here is the rough picture in today's money:
- $30,000 a year: about 37 years.
- $40,000 a year: about 20 years.
- $50,000 a year: about 14 years.
Notice the shape. Ten thousand dollars more spending a year does not shorten things a little. It can take well over a decade off the end. A slightly lower bill buys a lot of time.
Mara is 60 with $500,000 and spends $2,800 a month, about $33,600 a year. That is a pot that would be used up in about 28 years, so roughly to her late 80s. If she can trim to $1,600 a month, about $19,200 a year, the same pot is on track to keep going for good. Her savings did not change; her bill did.
Is $500,000 enough at 55? At 60?
Age changes the question because it changes how long the money has to last.
- At 55 you may need it for 40 years or more, so many people go lower than 4%. In the US, health cover before Medicare at 65 is a real cost, and the access rules for retirement accounts are worth reading up on first.
- At 60 the horizon is shorter, perhaps 30 years, which makes $500,000 go further. Many people also lean on a part-time job for the first few years to protect the pot.
Rules and costs differ by country. In the UK, Canada and elsewhere, state pensions, tax-free accounts and health costs work differently, so treat the examples here as a way to think, not a local answer.
What can you change?
- Spend a little less. The most powerful lever by far.
- Work a bit longer or part-time. Every year of income is a year you do not draw.
- Use other income. A pension or a paid-off home changes the bill the pot has to cover.
- Be flexible. Trimming spending in a bad year helps a pot survive.
Not sure which bills $500,000 could cover? In Untilfree you add your bills and the app shows which ones your savings already pay for, smallest first: "paid for, forever".
If you are still building toward this, our guide to how much money you need to never work again shows what moves the target, and the $1 million version shows how a bigger pot behaves.
Questions people ask
Can I retire early with $500K?
It is possible if your yearly spending is low, roughly $20,000 or less for a pot that lasts for good, or if you have other income. At higher spending the pot is used up over time, so many people combine it with part-time work.
How much will $500,000 earn per year in retirement?
Drawing 3% to 4% a year gives about $15,000 to $20,000 a year before tax. That is a guide for sustainable spending, not a guaranteed payout, and real returns vary from year to year.
Is $500K enough to retire at 55?
For most people not on its own, because the money may need to last 40 years and health cover costs money before Medicare at 65. With very low spending, other income or part-time work, it can be part of a workable plan.
Is $500K enough to retire at 60?
It can be, especially if you have Social Security to come at 62 or later, a paid-off home, and modest spending. The shorter horizon helps. Run your own spending through a calculator before deciding.
Is $500,000 enough to retire outside the US?
It depends on local costs, health care and pension rules, which differ by country. Cheaper places stretch a pot further, but check visas, tax and health cover first, because those can change the picture.
See what your savings already pay for
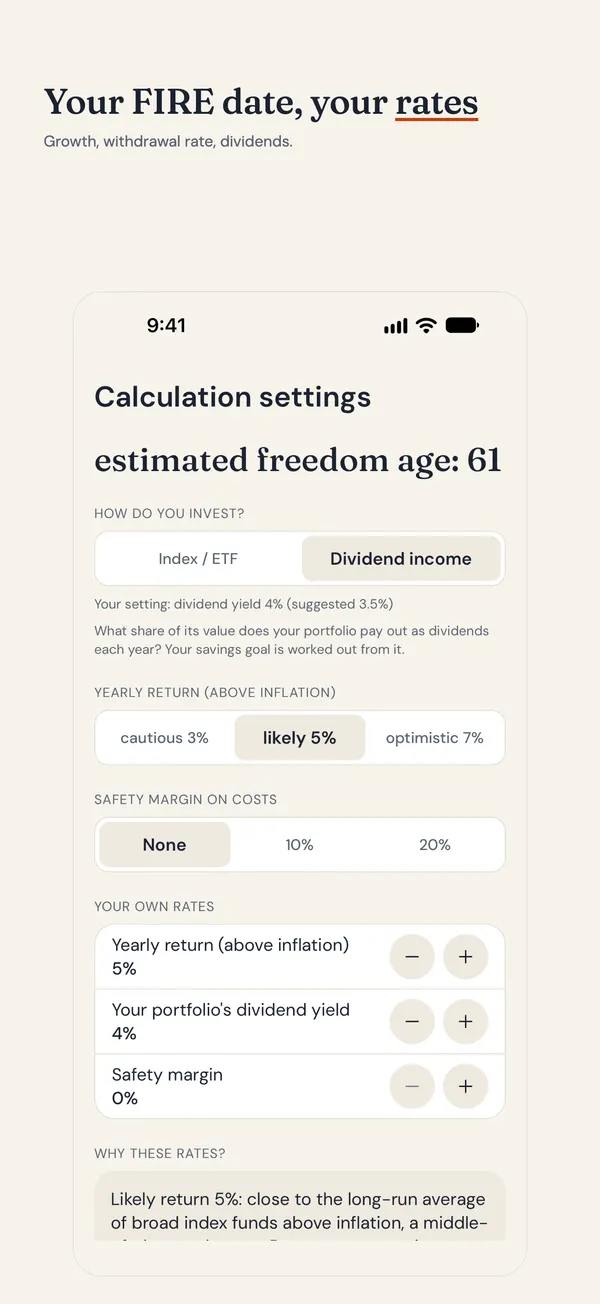
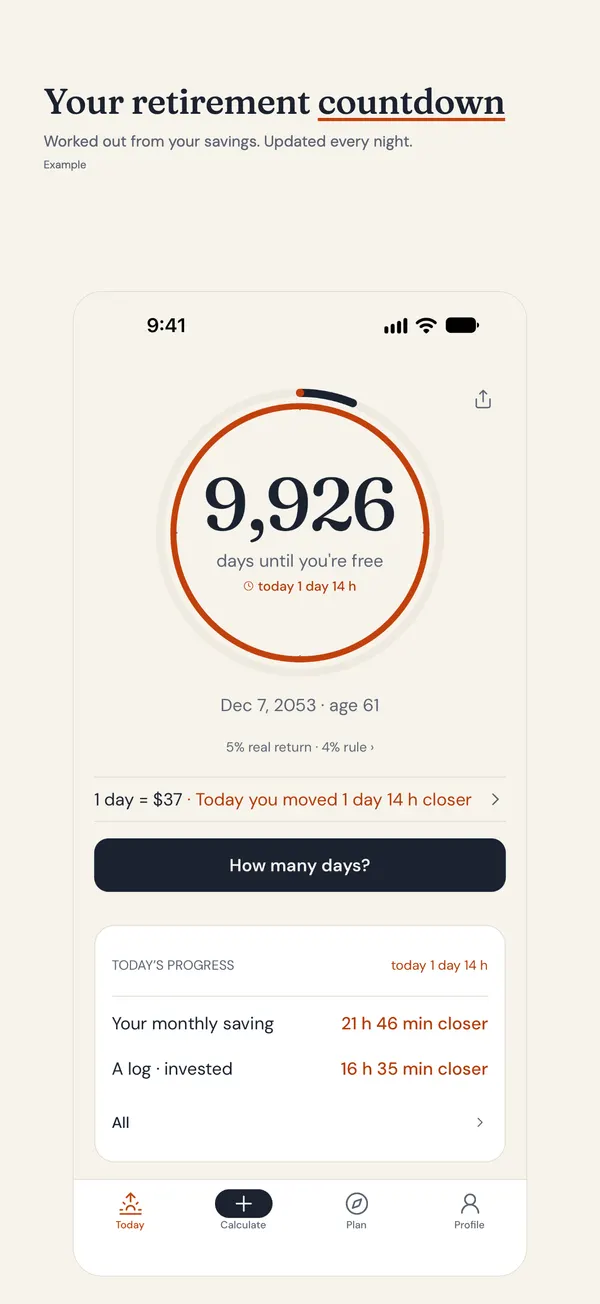
Enter your savings and your bills. Untilfree shows your exact freedom date, a cautious, likely and optimistic range, and which bills are already paid for, forever.
- Bills covered one by one
- Pick index funds (4%) or dividend income (3.5%), and adjust the rate
- No account and no bank link; numbers stay on your phone
App Store · Free · Ads, optional Plus · No account · No bank link
Untilfree gives estimates in today’s money (after inflation). Taxes and state pensions are not included. This page is general information, not investment advice.
Published · by Srofia