 Untilfree
FIRE Calculator: Your FIRE Number, Years to FI and Coast FIRE
Your FIRE number is about 25 times what you spend in a year: spend $40,000 and you need roughly $1 million invested. Enter your numbers below to see your FIRE number, how many years until you reach it, and your Coast FIRE number.
Updated · by Srofia
How the calculator works
- FIRE number = yearly spending ÷ withdrawal rate. At 4% that is 25× your spending; at 3.5% it is about 28.6×. Read more in what is your FIRE number and the 4% rule explained.
- Years to FI: your money now plus what you invest each month, grown month by month at your return after inflation, until it reaches the FIRE number. The biggest lever is your savings rate.
- Coast FIRE number = FIRE number ÷ (1 + return)years to retirement age. If you already have it, you could stop saving for retirement. See Coast FIRE explained.
Sam is 30, has $50,000 invested, invests $1,500 a month and spends $3,300 a month. At a 4% withdrawal rate Sam’s FIRE number is about $990,000. At 5% growth after inflation Sam gets there in about 24 years, around age 54. Sam’s Coast FIRE number for age 65 is about $179,000, so Sam isn’t coasting yet.
Lean, regular and fat FIRE
The same math works for any lifestyle; only the spending changes. Lean FIRE plans on a tight budget, Fat FIRE on a comfortable one, and Barista FIRE mixes savings with part-time work. If you are thinking about leaving a job sooner, see how much money you need to quit your job.
Questions people ask
How do I calculate my FIRE number?
Multiply what you spend in a year by 25. That is the same as dividing it by a 4% yearly withdrawal rate. Spending $40,000 a year gives a FIRE number of $1,000,000. A lower withdrawal rate, like 3.5%, gives a bigger and safer number.
How many years until I reach FIRE?
It depends mostly on your savings rate: how much of your take-home pay you invest. The calculator grows what you have now plus your monthly investing at your chosen return after inflation, month by month, until it reaches your FIRE number.
What is Coast FIRE?
Coast FIRE is the amount you need invested today so that, with no more saving, it grows into your full FIRE number by your retirement age. After that, work only has to pay today’s bills.
What return should I use?
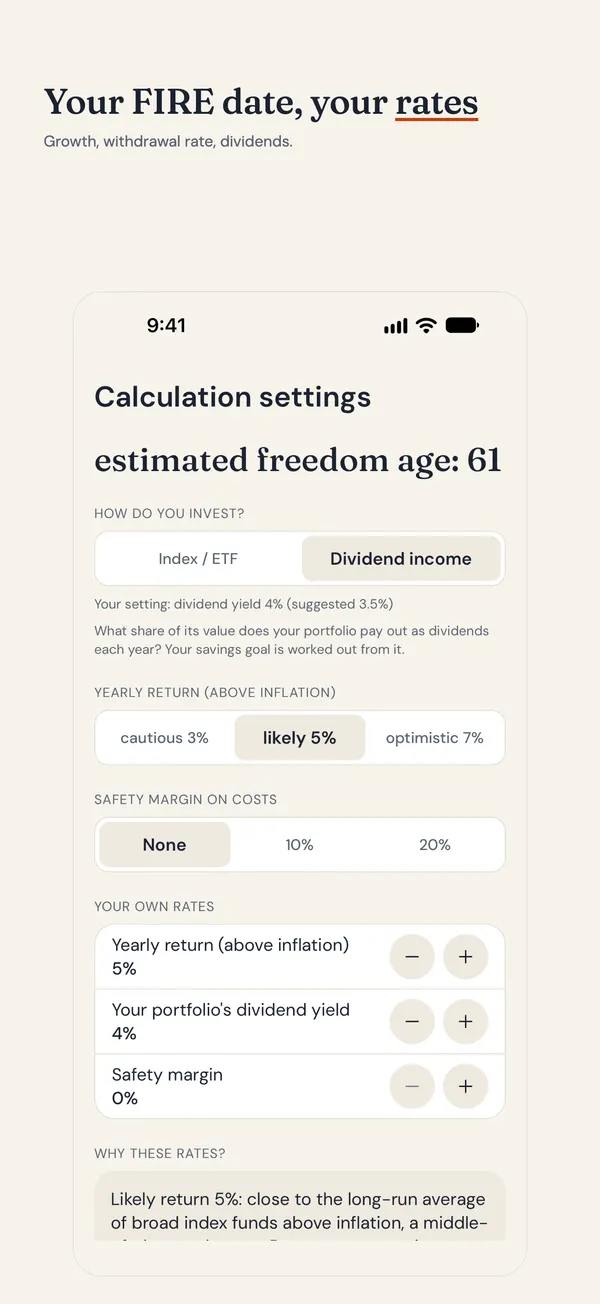
Use a return after inflation and lean cautious. Many people use 5% for a stock-heavy portfolio and test 3% to see how fragile the plan is. Results are in today’s money.
Is the 4% rule safe?
It comes from studies of past US market returns over 30-year retirements. For longer early retirements many people use 3.25% to 3.5% instead. You can change the rate in the calculator.
Does this calculator include taxes or pensions?
No. It is a rough plan in today’s money, without taxes, fees or state pensions. Use it as a starting point, not as financial advice.
Count down to the day you could stop working
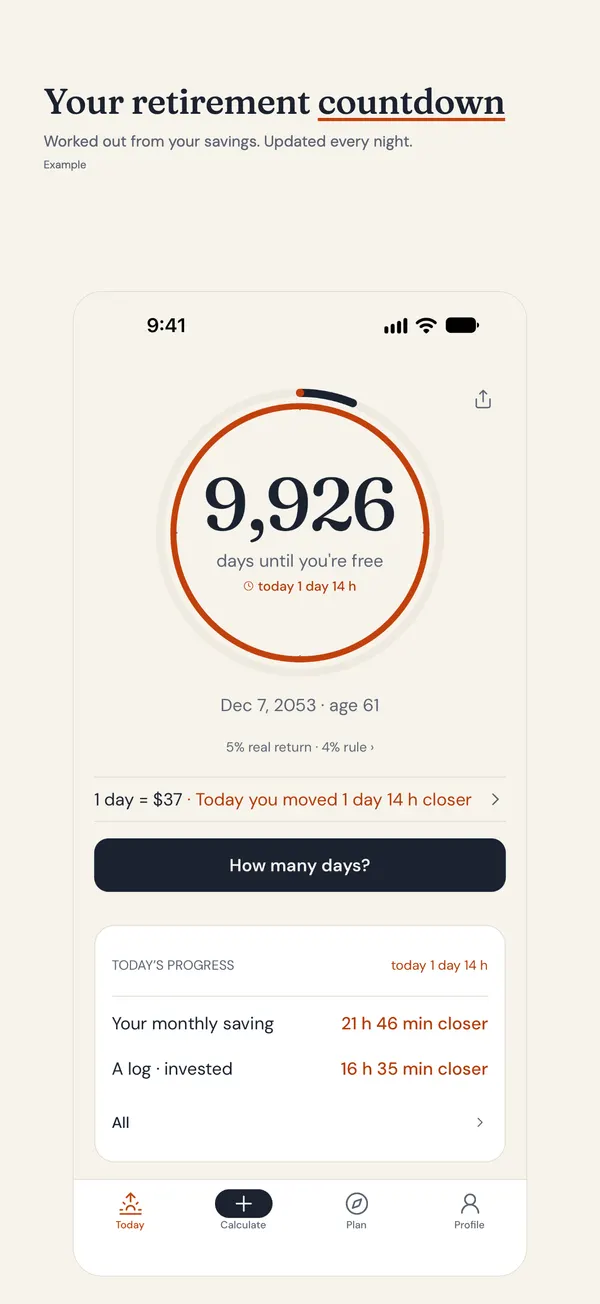
Four questions — your age, savings, monthly investing and monthly spending — and Untilfree gives you a date, then counts down every night to the day your savings could pay all your bills.
- Your full freedom day and how many days are left
- Cautious, likely and optimistic dates
- See how a raise or a cut moves the date
App Store · Google Play · Free · Ads, optional Plus · No account · No bank link
Estimates in today’s money (after inflation). Taxes, fees and state pensions are not included. This page is general information, not investment advice.